A higher median in the quietest October since 2010. Here’s what each number is actually telling you.
By Nick DiPasquale | November 8, 2026
Anyone who has raked a yard in October knows the pile can fool you. A big pile doesn’t necessarily mean the trees are bare, and a small one doesn’t necessarily mean they’re still holding on. The pile only tells you which trees let go that week.
October’s housing numbers work the same way.
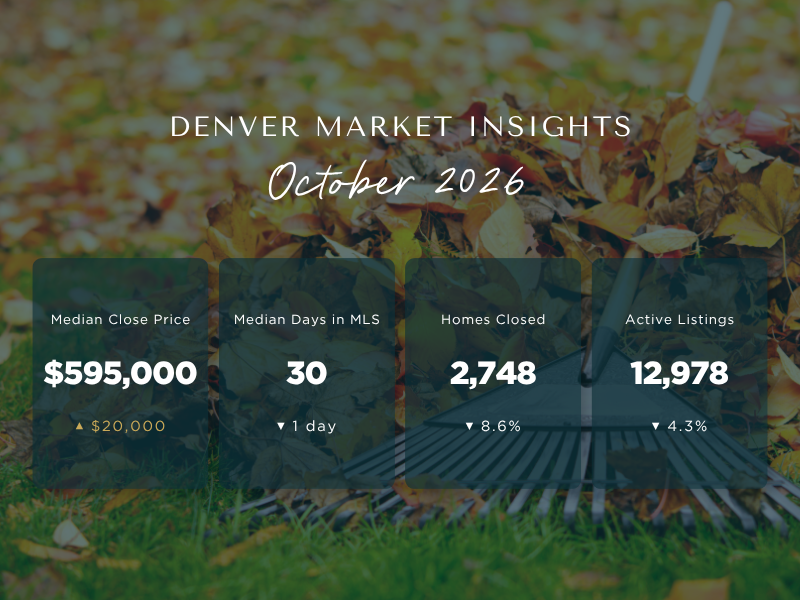
The median close price across the Denver metro rose $20,000 from September, to $595,000. In the same month, 2,748 homes closed, the fewest in any October since 2010, according to DMAR. One number says the market bounced back. The other says buyers have rarely been this quiet in the fall.
So which one tells the truth? Both do. They’re just answering different questions. The median tells you which homes sold. It doesn’t tell you what homes are worth.
What the Median Actually Measures
A median is the middle sale. Half of the homes that closed sold for more, half for less. That makes it resistant to a few extreme sales, but it has a blind spot: it moves whenever the mix of homes selling changes, even if no individual home is worth a dollar more.
That’s what happened in October. Detached and attached medians each rose exactly $10,000 from September. A look at which homes sold shows higher-priced homes made up a bigger share of sales in both categories. For detached homes, sales of $750,000 and up went from 34.3% of closings to 35.7%, because sales below that line fell faster. For attached homes, the shift was sharper. Total attached closings fell 11.9%, while attached sales of $1 million and up rose from 20 to 27.
Meanwhile, in the $500,000 to $749,999 range, which accounts for nearly two-thirds of attached sales above $500,000, price per square foot fell 5.0% from September. The median went up. The value of the space didn’t. And for context, October 2024 produced the exact same $20,000 jump from September. This is a pattern we’ve seen before, not a turning point.
Worth knowing: how a median can rise when no home gains value
- In September, five homes sell for $400,000, $500,000, $575,000, $650,000 and $800,000. The median is $575,000.
- In October, four homes sell at those same higher prices, but nothing sells at $400,000.
- The median jumps to $612,500. No home gained a dollar of value. The cheapest sale just dropped out of the count.
If the median is the number that flatters, the sales count is the one that doesn’t. Months of inventory, which measures how long it would take to sell every active listing at the current pace, sits at 4.72, up from 3.48 last October. That may look like a flood of new listings, but it isn’t. Active listings are up just 3.9% from a year ago, while closings are down 23.5%. Had Denver sold as many homes this October as last October, months of inventory would be at about 3.6, barely above last year.
Inventory didn’t surge. Sales slowed.
Where Sales Thinned Out Most
The gap between detached and attached homes keeps widening. Detached homes sold in a median of 26 days, four days faster than last October. Attached homes took 48 days, up from 41. Attached months of inventory sits at 7.26, compared with 4.05 for detached.
The share of the market tells the rest. Attached homes made up 21.0% of October’s closings and 32.4% of active listings, but 41.1% of the homes that came off the market unsold, based on our own REcolorado MLS data. That’s 1,060 attached homes unlisted against 578 sold, nearly twice as many leaving the market as closing. The pattern is consistent with sellers choosing to wait rather than adjust.
Part of this is monthly math. A condo or townhome may carry a lower price, but HOA dues and insurance sit on top of the mortgage from day one, and buyers are weighing the full cost of ownership, not just the purchase price. Savvy buyers do the same with detached homes, looking at the remaining life of the roof, furnace and water heater even when everything still works. With attached homes, a big piece of that future cost is already printed on the HOA statement.
For condo and townhome buyers, that means real negotiating room right now. For sellers, it means pricing to the full monthly cost a buyer will carry, not just the last comp.
The Signal Behind the Slowdown
Last month, I wrote that October would show the full impact of September’s rate increase. It did. Closings fell 8.6%.
The more important number is what comes next. Pending sales, the contracts signed in October that will close over the next four to six weeks, fell to 2,562, down 20.3% from last October. For the four previous Octobers, that number held in a tight range between 2,997 and 3,343. This October broke well below it, to the fewest October contracts in more than a decade. Pending sales always dip from September to October, but this year’s 7.3% drop was the steepest since 2022.
It’s not hard to find one of the main culprits behind this. Freddie Mac’s 30-year average stayed above 7% all month and closed October at 7.24%, a full point higher than a year earlier.
Sellers, by contrast, behaved like they usually do in the fall. New listings fell 16.7% from September, in line with past Octobers, and are down 9.0% from last year. What stands out is how many homes left the market unsold: 2,578, as many as went under contract, and 45.4% more than last October.
With fewer contracts in the pipeline than homes that closed in October, expect November closings to slip again.
The Discount That Doesn’t Show Up in the Price
There’s one more reason the median can look stronger than the market feels. According to DMAR, 65% of homes sold in October involved a seller concession, averaging $12,557. Credits toward closing costs or a rate buydown don’t change the recorded sale price, so they never show up in the median.
Worth knowing: what a concession does to the real price
- A home closes at the $595,000 median. That’s the price the public record shows.
- An average concession of $12,557 equals about 2.1% of that price.
- The seller walks away with closer to $582,443 before other costs.
Multiply that across nearly two out of every three sales, and what Denver sellers actually net is quietly lower than the headline says.
For buyers, that’s the opportunity. In a market with more homes than active buyers, much of the negotiation has moved into the terms. For sellers, it’s a reality check. If you’re measuring your home against a neighbor’s recorded sale price, you may not be seeing what they actually walked away with.
The price held. The terms moved.
The Bottom Line
October’s market is quieter than its prices suggest. Fewer buyers are signing contracts, more sellers are stepping back, and the median rose mostly because of which homes sold, not because homes gained value.
That’s why the headline numbers can’t tell you what your home is worth or what you should offer. A condo seller, a detached buyer under $750,000 and someone shopping above $1 million are each working in a different market right now. Like that pile of leaves, the median only tells you which trees let go.
If you’re trying to figure out which numbers apply to you, we’d be glad to work through them together.
Data from DMAR’s November 2026 Market Trends Report (October 2026 data), provided by REcolorado. Unlisted listing data from Nookhaven’s REcolorado MLS data pull. Mortgage rates from Freddie Mac’s Primary Mortgage Market Survey.
We love sharing thoughtful perspectives on home, place, and everyday living. If this sparks a question or curiosity, we’d always be glad to connect and continue the conversation here.