The most September inventory since 2011 and a sharp rise in homes pulled from the market are two sides of the same decision.
By Nick DiPasquale | October 5, 2026
September’s numbers show Denver sellers making two very different decisions at the same time.
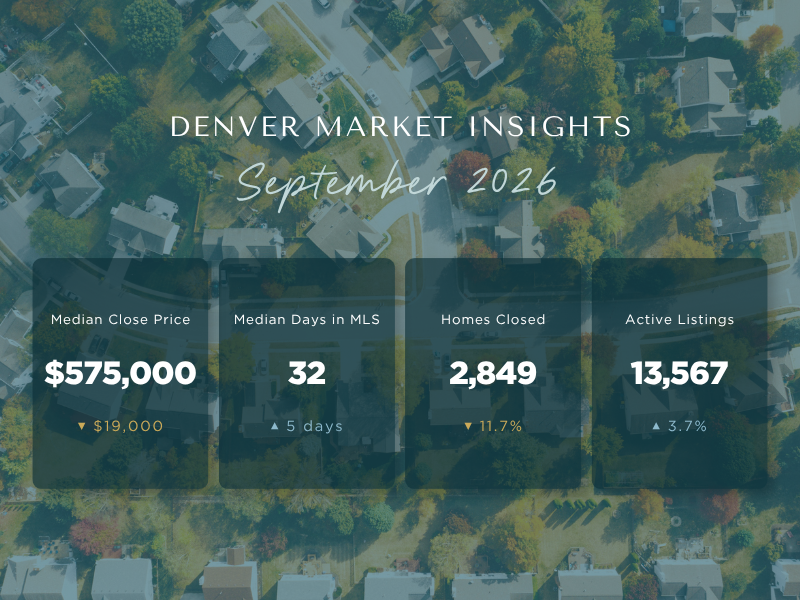
Denver metro closed the month with 13,567 active listings, the most for any September since 2011. Inventory grew 3.7% from August, nearly five times the typical August-to-September increase. A lot of sellers stayed put.
At the same time, 2,413 homes came off the market without selling, 31% more than last September.
Some sellers held on. Others stepped back. Both groups were looking at the same market and the same buyers.
That’s the tension sellers are carrying into the fall: hold through the season and meet today’s buyer, or pull the listing and try again in spring. Either can be the right call, depending on the seller. Making it well means understanding what’s happening on the other side of the table, where buyers are working with budgets that shrank a little more every week rates climbed.
The Inventory Count Misses Half the Story
Active listings only count homes for sale on the last day of the month. They don’t count homes that left without selling.
From July through September, 6,976 homes came off the market unsold, up 31% from last year and more than double the same stretch in 2024. September did ease slightly from August, the first monthly decline since February, but the pace remains well above recent years.
Those homes didn’t disappear. Their owners haven’t sold. Some of that is consistent with sellers waiting for a better time to sell; some may be pausing altogether. Either way, there are more homes waiting to sell than active listings show.
Days on market has the same blind spot. Median days in MLS only counts homes that sold. A listing that sat for 90 days and was withdrawn never shows up in it. When the data says the typical home sold in 32 days, it’s describing the homes that found a buyer.
It says nothing about the ones that didn’t.
What Sellers Are Up Against: The Buyer’s Budget
On paper, September should have given buyers a little relief. The median close price fell $19,000, to $575,000, and a lower price usually means more buying power for the same home.
Rates moved the other way. Mortgage rates climbed every week in September, reaching about 7.5% by month’s end, up from roughly 6.7% in August. For a buyer putting 20% down, the monthly principal and interest on that median home went up about $150, even after the price drop. To hold the payment where it was in August, the median would have needed to fall about $46,000.
Prices fell. Payments rose.
Worth knowing: Here’s where the $46,000 comes from. In August, the $594,000 median with 20% down at about 6.7% meant roughly $3,066 a month in principal and interest. At 7.5%, that same $3,066 supports a loan of about $438,500, which with 20% down is a home of about $548,000. That’s roughly $46,000 less house for the same monthly budget. This is principal and interest only; taxes, insurance, and any HOA dues aren’t included.
The Federal Reserve added pressure. On September 16, it raised its benchmark rate a quarter point, to 3.75%–4.00%, its first increase since 2023. Confidence is slipping too: consumer confidence fell to its lowest level since 2014, Colorado lost 1,400 jobs in August, and labor-force participation hit its lowest point on record dating back to 1976. Even buyers who qualify for a loan may hold off when they’re uneasy about their jobs or the economy.
The result shows up in pending sales, the clearest signal of where closings are headed. Buyers put 2,908 homes under contract in September, the fewest September contracts in more than a decade and 13.4% below last year. That pullback started earlier this year. Through the first half of the year, contracts were running roughly even with last year. Then they fell about 10% behind in July and about 15% in August.
Sellers, meanwhile, kept listing at August’s pace. Those homes were planned weeks or months ago, and they came to market the same month the Fed raised rates for the first time since 2023.
Condo and Townhome Sellers Feel It Most
Detached homes held their ground. The detached median of $635,000 is exactly where it was last September. Attached homes did not: the attached median of $365,500 is down $24,500 from a year ago, and the typical attached home took 44 days to sell, compared with 28 for detached.
Attached homes made up 22% of September’s closings, but 33% of active listings and 40% of homes pulled from the market. Attached buyers carry HOA dues on top of the mortgage, so a higher rate squeezes a monthly budget that’s already partly spoken for. Attached sellers are feeling the tension more than anyone.
Holding Through Fall vs. Waiting for Spring
For sellers who stay, the job is pricing for the buyer who is shopping right now, at today’s rates, with less buying power than a buyer had even a month ago.
Staying also comes with an advantage. Active listings typically taper through the fourth quarter as some sellers pull their homes for the holidays. The sellers who remain face less competition for the buyers who are still looking.
For sellers who step back, the bet is on spring. Spring brings more buyers, but it brings more sellers too. This April, new listings ran about 36% higher than this September, and that was before counting any of this year’s withdrawn homes that may return. The Fed’s own projections keep its benchmark rate elevated through 2027.
Waiting works best if spring’s buyer can pay more than today’s. That’s a bet, not a given.
The Bottom Line
This is a market where sellers are split between holding on and stepping back, and buyers’ shrinking budgets are what make the choice so hard. Rates are moving faster than prices, and every seller decision this fall runs through that gap.
The right call depends on the specifics: your home type, your price point, your timeline, and how much flexibility you have. For buyers, there’s more room to negotiate on price now than at any point this spring or summer, with 4.76 months of inventory squarely in balanced territory. But with rates moving week to week, the monthly payment can shift between the day you start looking and the day you write an offer. Check in with your lender often, and make sure the full payment, including taxes, insurance, and any HOA dues, still fits before you commit.
If you’re weighing whether to hold, step back, or make a move, we’d be glad to work through the numbers with you.
Market data sourced from the Denver Metro Association of Realtors® September 2026 Market Trends Report. Data provided by REcolorado. Withdrawn listing data from Nookhaven’s REcolorado MLS data pull.
We love sharing thoughtful perspectives on home, place, and everyday living. If this sparks a question or curiosity, we’d always be glad to connect and continue the conversation here.